 dailynewsnblog
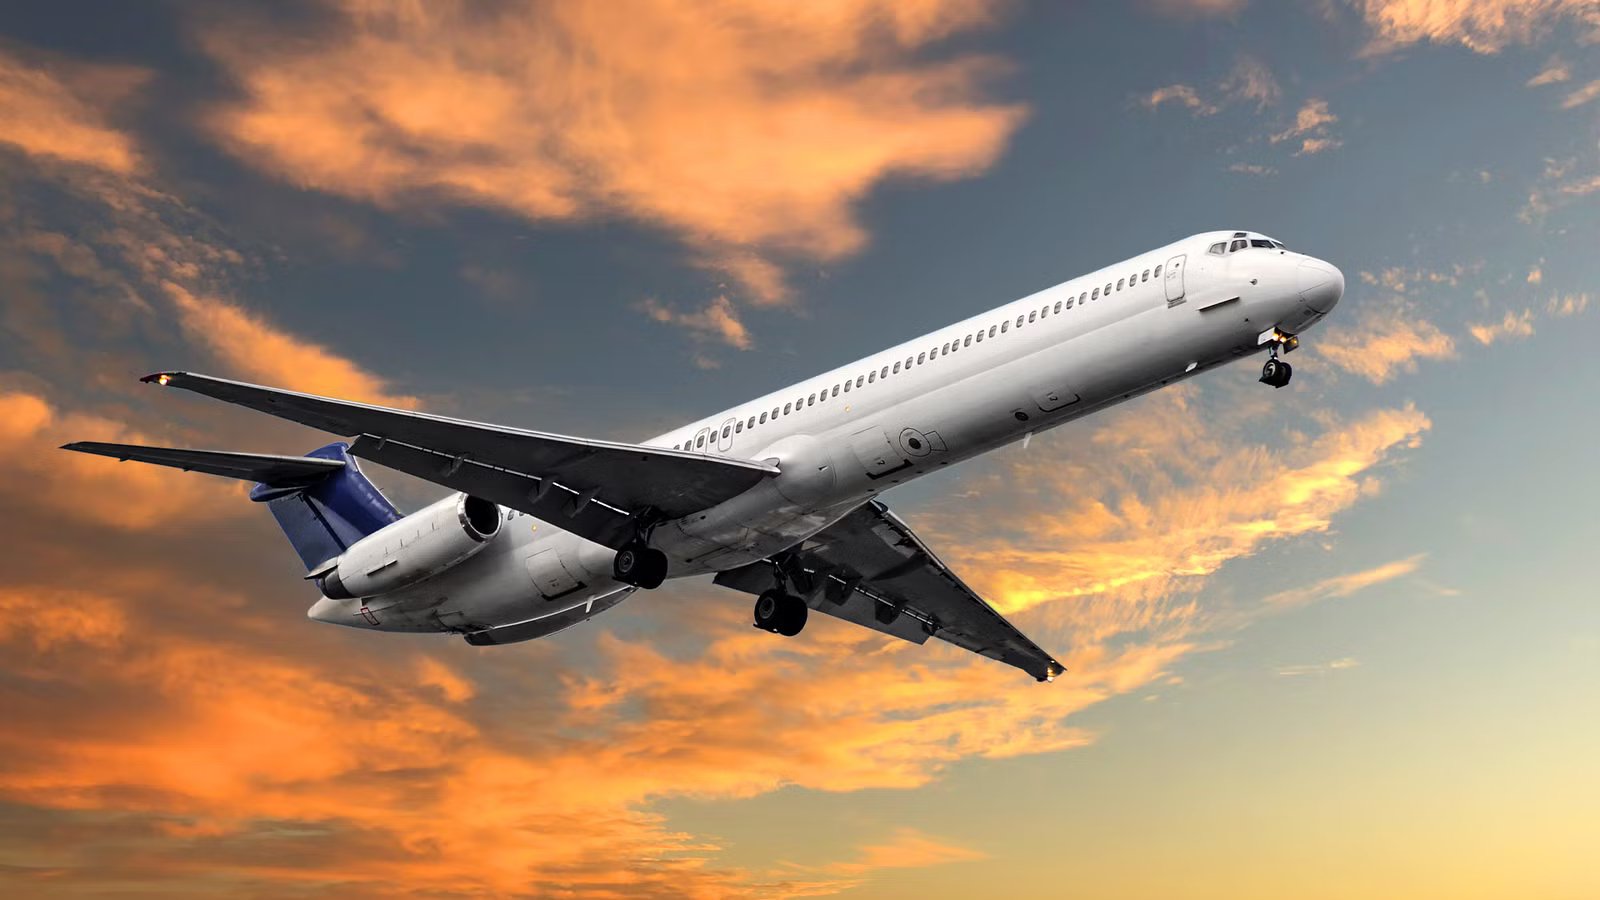
Loud Pratt & WhitneyJT8D engines that powered rocket-like takeoffs have slowly been disappearing from the skies. Significant reduction in the global fleet occurred when  Delta Air Lines and
 American Airlines accelerated retirements of the type in the early 2020s. Manufactured by McDonnell Douglas, the program was sold to
 Boeing in 1997 as a result of a merger, as originally reported by The Spokesman Review.
However, the McDonnell Douglas MD-80, also nicknamed the “Mad-dog,” still pops up in erratic appearances across airfields and airways worldwide. While not entirely obsolete, the US-manufactured airframe has been phased out of fleets primarily due to the presence of older technology and less efficient fuel burn. The CFM LEAP engine burns roughly 35% to 40% less fuel than the older JT8D low-bypass turbofan.
The Jet That Refuses To Disappear

The MD-80 program has historically been a huge success, with a total of 1,191 to 1,194 aircraft built between 1979 and 1999. At its peak in the early 2000s, American operated a fleet of over 360 airframes, and Delta close behind at 243. Alitalia was the largest operator of the program outside of North America, tallying its fleet at around 90.
That success translated into remarkable longevity. Even as newer types such as the Boeing 737 family and Airbus A320 series offered improved fuel efficiency and lower operating costs, hundreds of MD-80s remained active well into the 2010s. Airlines that had invested heavily in the type often found the economics of keeping fully paid-for aircraft in service more attractive than financing large replacement orders. This strategy continues today for several operators, even with Delta, while having retired the MD-80 and McDonnell Douglas MD-90series, keeping their Boeing 717s in service.
The 717 was formerly known as the McDonnell Douglas MD-95 before the merger with Boeing and the program’s integration, and it was the most modern edition of the family. On the other end of the family tree lies the similar-looking McDonnell Douglas DC-9, the predecessor to the MD-80. This jet was produced from 1965 to 1982, and 976 units were made during this 17-year production run.
Who Still Operates the MD-80 Today?

The answer is a surprisingly diverse mix of cargo companies, charter specialists, and airlines operating in markets where acquiring newer aircraft can be difficult or prohibitively expensive. According to FlightQ’s current fleet data, five airlines still operate the MD-80, with 21 aircraft in active service. The largest operator is USA Jet Airlines with eight aircraft, followed by Mexico’s Aeronaves TSM and Iran Airtour with four each, alongside World Atlantic Airlines and Venezuela’s Rutaca.
The picture broadens further when you look beyond passenger airlines. Fleet databases show MD-80 variants still flying in cargo, charter, and specialized roles across several regions, particularly in Iran, Venezuela, Mexico, and North America. The aircraft’s continued presence is partly due to its robust design and the availability of used airframes and spare parts, allowing operators to keep acquisition costs low compared to newer-generation jets. While only a fraction of the more than 1,190 aircraft built remain active, industry fleet trackers still record around 100 MD-80-family aircraft flying worldwide in various capacities.
Operator | Country | Fleet Size |
USA Jet Airlines | United States | 8 |
Aeronaves TSM | Mexico | 4 |
Iran Airtour | Iran | 4 |
World Atlantic Airlines | United States | 3 |
Rutaca Airlines | Venezuela | 2 |
Total | 4 Countries | 21 |
Yet longevity alone does not explain why operators continue to accept the type’s fuel burn, noise profile, and aging systems. The MD-80 also resists many modern aviation sustainability initiatives because of its outdated fuel-efficiency ratings. If modern aircraft are demonstrably more efficient, what exactly makes the MD-80 economically viable in 2026?
Why The MD-80 Still Works Today

The MD-80 remains viable not because it can compete with modern narrowbodies on fuel efficiency, but because many of the aircraft still flying have long since been paid off. For operators flying limited schedules, charter missions, cargo services, or routes with relatively low utilization, avoiding the capital cost of newer aircraft can outweigh the fuel penalty.
According to FlightQ, the largest active MD-80 operator is USA Jet Airlines with eight aircraft, followed by Mexico’s Aeronaves TSM and Iran Airtour with four each. Most of these carriers operate outside the highly competitive environments that pushed major airlines such as American and Delta to retire the type years ago. Instead, they use the aircraft in cargo, charter, or regional operations, where lower acquisition costs can matter more than maximizing fuel efficiency for high-frequency schedules.
However, as these aircraft age, spare parts become harder to source, and maintenance requirements become more demanding. Luckily, the program still has a somewhat intact supply chain, except for sanctions against Iran and Venezuela. For example, NEDAVION Aerospace explicitly runs dedicated MD-80 teardown programs, procuring retired legacy MD-82 and MD-83 airframes. If the MD-80 can still work economically today, the next question is how much longer operators can realistically keep the “Mad Dog” flying before age finally catches up with it.
Pressures Closing In

As fleets shrink, operators lose many of the scale advantages that once supported the type. Training pipelines become harder to sustain, specialized maintenance expertise becomes less common, and sourcing components for a fleet that left production in 1999 becomes increasingly difficult. The economics that favor a fully depreciated aircraft today can quickly reverse when maintenance costs rise faster than the value the aircraft generates.
During production, McDonnell Douglas and, later, Boeing offered a new, rotable parts marketplace that mirrors the 737NG program today. However, 1999 signaled the end of official Original Equipment Manufacturer (OEM) support. This funneled all supply chain and technical operation needs to the aftermarket, providing demand for companies like NEDAVION and Pilot John International.
With those changes in mind, any operator willing to accept the trade-off of a weaker supply chain in pursuit of a lower barrier to entry may do so. Operators may also continue operating such an aircraft because of its novelty. A similar exhibition took place with John Travolta’s Boeing 707.
How Operators Adapt In 2026

For the operators that still fly the MD-80, survival depends less on finding new aircraft and more on extracting value from the ones they already own. Rather than replacing aircraft on a fixed timeline, they are adapting through intensive maintenance planning, parts pooling, and the strategic acquisition of retired airframes for spares. Success depends not on fuel burn alone, but on an operator’s ability to secure engines, components, technical expertise, and maintenance capacity at a sustainable cost.
American Airlines historically spread support costs across more than 360 MD-80s, while Delta operated 243 at its peak. Today’s largest active operator, USA Jet, flies just eight MD-80s, while Aeronaves TSM and Iran Airtour operate four each. Rather than benefiting from scale, these carriers rely on specialization.
The MD-80 support ecosystem has shifted from manufacturing-driven to inventory-driven, with retired aircraft now playing a central role in sustaining active fleets. There is a capped number of materials and component programs still in active production for the MD-80 family. While not yet quantifiable, the number of operable years for these jets is limited.
How Much Longer Can It Survive?

The future of the MD-80 is likely to be determined less by the condition of the aircraft themselves and more by the economics surrounding them. Many of the remaining examples are flying relatively low-utilization missions where acquisition costs matter more than maximizing fuel efficiency. As long as operators can continue sourcing engines, components, and maintenance expertise at a reasonable cost, the aircraft can remain viable in niches that larger airlines abandoned years ago.
One metric worth watching is the size of the active operator base itself. FlightQ currently tracks just five airlines operating 21 MD-80s, led by USA Jet Airlines, Aeronaves TSM, and Iran Airtour. Each time one of these operators retires aircraft without replacement, the global support network shrinks. Conversely, when operators acquire retired airframes for parts, they can extend the economic life of the remaining fleet for years. The outcome may therefore depend less on age limits or airframe hours than on how long enough aircraft remain active to sustain the market for maintenance and spare parts.
Perhaps the most remarkable aspect of the MD-80 story is that the aircraft has repeatedly outlived predictions of its demise. The “Mad Dog” has already survived the rise of next-generation narrowbodies, major airline retirements, and the consolidation of the global airline industry. Whether it remains in service for another five years or another fifteen may ultimately be decided by a handful of operators in places where the aircraft still fills a role that newer jets cannot economically replace. For aviation enthusiasts, the most interesting number to watch isn’t the age of the newest MD-80, but the size of the fleet that remains after the next round of retirements.