 dailynewsnblog
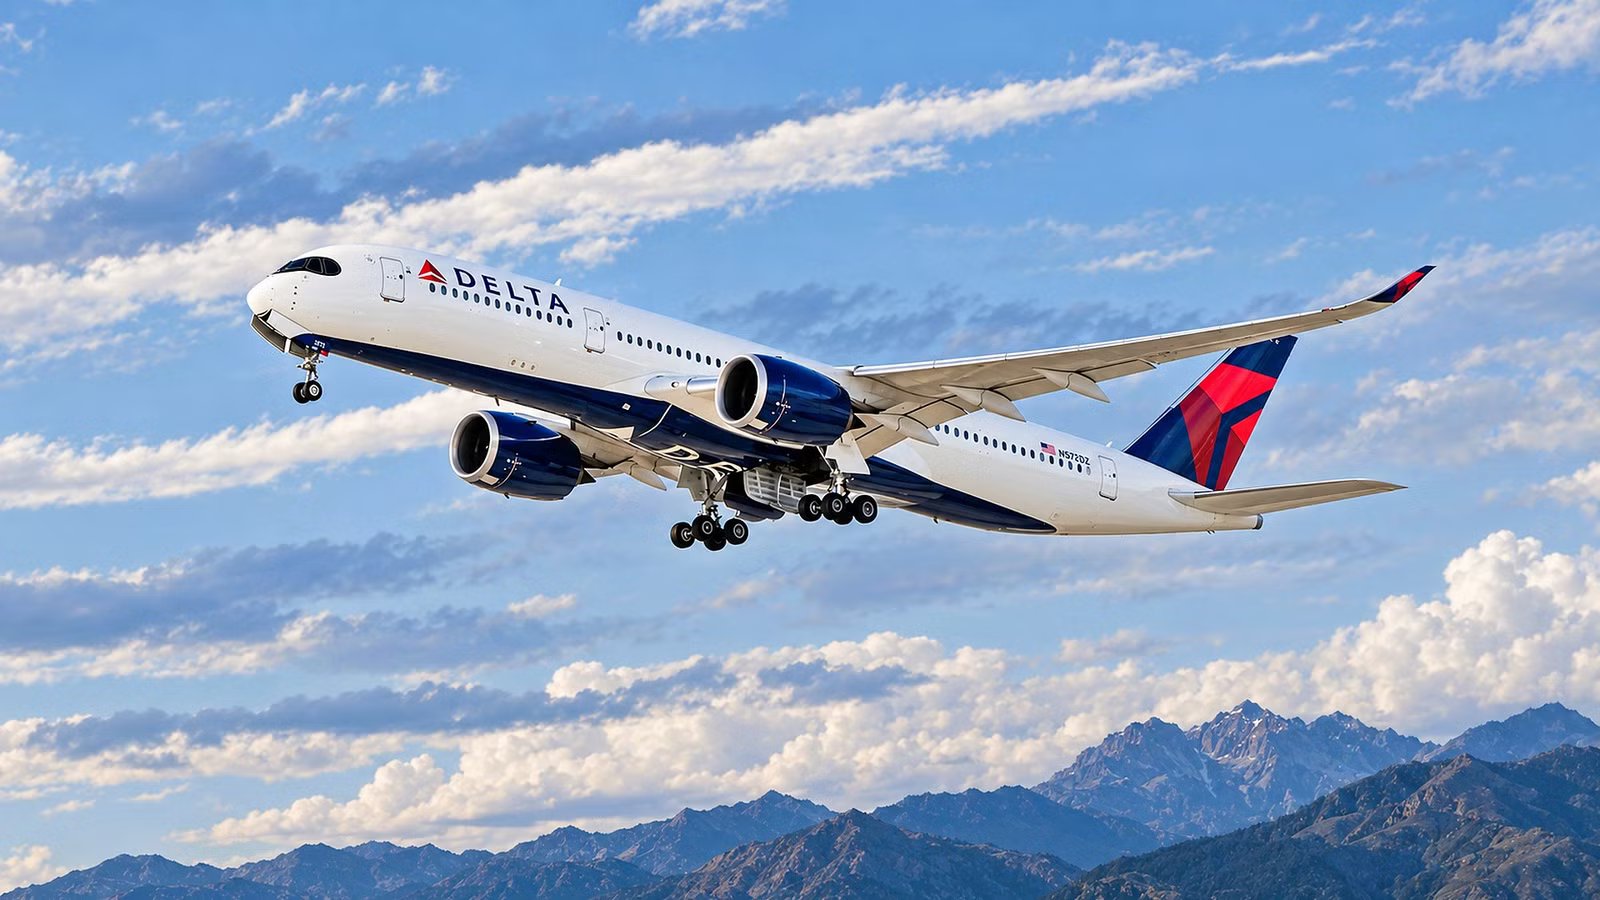
 Delta Air Lines is the most profitable US airline, and operates a massive network with over 5,500 daily departures to more than 300 destinations. Over the past decade, network capacity has grown 16%, but interestingly, Delta has also cut 21 long-haul destinations from its network. The list ranges from global business centers such as Singapore, Beijing, and Dubai to European “staple” destinations including Düsseldorf, Geneva, and Manchester.
Yet this is not the story of an airline retreating internationally, as Delta’s summer 2026 schedule was its largest ever. Instead, the vanished destinations offer a window into a much larger transformation. The airline has taken a journey from the depths of Chapter 11 bankruptcy to the pinnacle of US commercial aviation, where it now generates more than 55% of the adjusted earnings produced by all US airlines.
Delta achieved this massive transformation by becoming increasingly selective about which journeys it operates itself, which customers it targets, and what it believes each expensive widebody aircraft must earn. So let’s take a closer look at the 21 long-haul destinations cut over the past decade, as they tell the story of Delta’s remarkable turnaround.
Delta No Longer Needs To Fly Everywhere Itself

The 21 destinations did not disappear together. Four were gone by the end of 2016, another wave disappeared before 2020, and several — including Beijing, Osaka and Mumbai — fell away amid the pandemic. More recently, Delta removed Stuttgart in 2024 and Geneva, Gatwick and Tahiti in 2025. Taken together, however, the cuts demonstrate how dramatically the carrier’s long-haul map has been redrawn.
Destination | Last Delta-operated route | Distance | Last Served | Aircraft Used |
|---|---|---|---|---|
Bangkok | NRT–BKK | 2,889 miles (4,649 km) | 2016 | Boeing 767-300ER |
Beijing | DTW–PEK | 6,632 miles (10,673 km) | 2020 | Airbus A350-900 |
Brasília | MCO–BSB | 3,810 miles (6,130 km) | 2016 | Boeing 757-200 |
Dubai | ATL–DXB | 7,599 miles (12,229 km) | 2016 | Boeing 777-200LR |
Dubrovnik | JFK–DBV | 4,512 miles (7,261 km) | 2021 | Boeing 767-300ER |
Düsseldorf | ATL–DUS | 4,507 miles (7,253 km) | 2023 | Boeing 767-300ER |
Fukuoka | HNL–FUK | 4,397 miles (7,076 km) | 2019 | Boeing 767-300ER |
Geneva | JFK–GVA | 3,864 miles (6,218 km) | 2025 | Boeing 767-300ER |
Glasgow | JFK–GLA | 3,216 miles (5,176 km) | 2019 | Boeing 757-200 |
London Gatwick | JFK–LGW | 3,470 miles (5,584 km) | 2025 | Boeing 767-300ER |
Malaga | JFK–AGP | 3,658 miles (5,887 km) | 2019 | Boeing 757-200 |
Manchester | JFK–MAN | 3,341 miles (5,377 km) | 2017 | Boeing 767-300ER |
Moscow | JFK–SVO | 4,661 miles (7,501 km) | 2017 | Boeing 767-300ER |
Mumbai | JFK–BOM | 7,783 miles (12,525 km) | 2020 | Boeing 777-200LR |
Nagoya | DTW–NGO | 6,545 miles (10,533 km) | 2023 | Airbus A330-200 |
Osaka | SEA–KIX | 5,040 miles (8,111 km) | 2020 | Boeing 767-300ER |
Papeete | LAX–PPT | 4,095 miles (6,590 km) | 2025 | Boeing 767-300ER |
Pisa | JFK–PSA | 4,131 miles (6,648 km) | 2016 | Boeing 757-200 |
Ponta Delgada | JFK–PDL | 2,557 miles (4,115 km) | 2019 | Boeing 757-200 |
Singapore | NRT–SIN | 3,324 miles (5,349 km) | 2019 | Boeing 767-300ER |
Stuttgart | ATL–STR | 4,682 miles (7,535 km) | 2024 | Boeing 767-300ER |
Asia shows the strategic shift most clearly. Delta inherited Northwest Airlines‘ hub at  Tokyo Narita Airport (NRT), allowing passengers to fly Delta to Tokyo and then continue on another Delta aircraft to destinations across Asia. But the airline was dismantling that structure before the pandemic as it shifted its Tokyo flights to
 Tokyo Haneda Airport (HND). In place of Narita, Delta turned to
 SkyTeam partner Korean Air, and used their joint venture to form a hub at Seoul’s
 Incheon International Airport (ICN). Today, Delta says the two airlines connect more than 2,000 passengers each way daily through Incheon:
“Delta customers can continue to reach Singapore – and more than 80 other destinations throughout Asia – through Seoul-Incheon via the airline’s partnership with Korean Air.”
Europe works on the same principle. Delta’s joint venture with Air France-KLM and Virgin Atlantic coordinates schedules, pricing, revenue management and network planning, while sharing economics on covered traffic. That means that abandoning its own nonstop to Geneva does not mean abandoning every Geneva passenger: customers can travel via  Amsterdam Schiphol Airport (AMS) or
 Paris Charles De Gaulle Airport (CDG) while Delta redeploys that aircraft to more profitable options. And increasingly, those options are leisure-centric.
The New Network Follows A Completely Different Traveler

The changes in nonstop long-haul destinations striking. Delta has discarded Düsseldorf, Manchester, Stuttgart, Glasgow and Geneva, yet added or expanded in places such as Sardinia, Malta, Catania, Porto, Marrakech and Naples. Those aren’t perfect categories — business travelers visit Naples and vacationers visit Stuttgart — but the center of gravity has clearly moved toward premium leisure and experience-led travel. In many respects, that has resulted in a “second generation” network:
Characteristic | First Generation: Mid-2010s | Second Generation: Mid-2020s |
|---|---|---|
Core objective | Broad geographic coverage | Maximize return from each aircraft |
Asia | Delta-operated Narita connecting network | Select Delta gateways + Korean Air/Seoul |
Europe | More own-metal secondary/business cities | JV hubs + selective high-return spokes |
Typical European markets | Stuttgart, Düsseldorf, Manchester, Glasgow, Geneva | Sardinia, Malta, Catania, Porto, Marrakech, Naples |
Demand emphasis | Corporate/business + traditional international traffic | Corporate + premium leisure/experiential travel |
Seasonality | Greater continuity for established routes | Aircraft increasingly follow seasonal demand |
Loyalty | Primarily airline frequent-flyer relationship | Broader American Express / SkyMiles ecosystem |
Revenue priorities | Coverage, connectivity and load factor | Yield, premium mix, loyalty and aircraft opportunity cost |
Delta’s own network planners say customers now value experiences far more than before the pandemic, while aircraft can be shifted as demand changes throughout the year. That makes a Mediterranean destination viable even if it only works during summer, so the likes of Catania, Sardinia, and Malta are added as high-value seasonal opportunities. Of course, Delta is not the only one to have recognized the trend — its largest competitor is doing the same — but it is excelling at converting changing travel patterns into margin because it has some not-so-secret weapons.
SkyMiles, the world’s most valuable airline loyalty program, is one of them. It has been instrumental in Delta driving up the yields of its aircraft via more premium offerings, as well as remaining formidable in corporate travel — it ranked first in the Business Travel News airline survey for a 15th consecutive year last year.
But the even bigger lever is its partnership with American Express, which increasingly lets it monetize affluent customers outside the aircraft. Delta says its co-brand revenue is tied to broader consumer spending, while newer SkyMiles partnerships are embedding the currency in everyday life. Consequently, Amex remuneration has quadrupled since the middle of the last decade, and Delta is therefore responding by designing its network around where its most valuable (and affluent) customers want to go. That means more Marrakech and less Manchester.
Metric | 2015 | 2023 | 2025 | Change from 2015 |
|---|---|---|---|---|
Premium revenue | $10.1 billion | $19.0 billion | $22.2 billion | +120% |
American Express remuneration | $2.0 billion | $6.8 billion | $8.2 billion | +310% |
Share of U.S. peer-group earnings* | 30% | 40% | 55%+ | +25+ pts |
Perhaps nothing illustrates the change better than Delta’s 2025 “Route Race.” Nearly 150,000 votes were cast, SkyMiles members chose Sardinia, employees preferred Malta — and Delta launched both. A loyalty program once principally designed to reward flying is therefore helping shape where the airline flies. The modern high-value customer can earn miles through daily spending and then use that relationship for a premium Mediterranean vacation.
How Delta’s Fleet Drives Network Changes

None of this works without different aircraft economics. Ten years ago, Delta’s long-haul operation depended heavily on Boeing 767s, older Airbus A330s and Boeing 777s. Since then, the A350-900 and A330-900neo have arrived, Premium Select has spread through the widebody fleet, and Delta is now preparing for the A350-1000.
Most importantly, the fleet renewal has explicitly added premium capacity (see table below), with the percentage of premium seats aboard Delta’s widebodies edging ever-closer to a third of the aircraft. This, while simultaneously improving fuel efficiency, leads to significantly improved margins.
Aircraft/Configuration | Delta Era | Total Seats | Premium Seats | Premium Share |
|---|---|---|---|---|
Boeing 767-300ER, 225-seat layout | Earlier generation | 225 | 25 | 11% |
Airbus A330-200, earlier layout | Earlier generation | 234 | 34 | 14% |
Airbus A330-900 | Current | 281 | 57 | 21% |
Airbus A350-900, 275-seat layout | Current | 275 | 80 | 29% |
Airbus A350-1000 | From 2027 | 304 | 101 | 33% |
This means that load factor measures, which for so long were the key performance indicators that determined whether a route continued or not, have become only part of the equation. Why? Because it’s no longer enough to fill an aircraft, it’s as much about which cabins are being filled. We can see this in the numbers: Delta generated $22.1 billion of premium ticket revenue in 2025, almost matching its $23.4 billion Main Cabin business, while premium revenue grew as Main Cabin revenue declined.
Delta’s discontinued route from  Hartsfield-Jackson Atlanta International Airport (ATL) to Stuttgart Airport (STR) is a case in point. The route had delivered strong load factors of 84–85% for years, yet capacity was dramatically reduced between 2019 and 2024 in order to maintain those levels. But the high load factor alone says nothing about fares, premium revenue, cargo, frequency economics or the opportunity cost of deploying that widebody elsewhere. Eventually, Delta decided that the aircraft could deliver better yields on more premium-centric transatlantic routes.
ATL–Stuttgart | Round-Trip Passengers | Load Factor | Vs. 2019 Passengers |
|---|---|---|---|
2019 | 130,273 | 84.24% | — |
2023 | 45,003 | 84.98% | -65.5% |
2024 | 43,768 | 84.99% | -66.4% |
That is ultimately what the 21 canceled airports reveal. Delta’s long-haul map increasingly resembles an actively managed portfolio: partners provide breadth, SkyMiles and American Express increase the value of a customer far beyond their ticket, seasonal routes chase changing demand, and newer widebodies carry far more premium inventory. Which means Stuttgart can be 85% full and still lose; Sardinia can operate for only a season and still win. For today’s Delta, the pin on the map matters less than the return it produces.