 dailynewsnblog

Listen to this article
Estimated 2 minutes
The audio version of this article is generated by AI-based technology. Mispronunciations can occur. We are working with our partners to continually review and improve the results.
The government announced a major tax reform at the Canada Investment Summit that will allow businesses to write off investments in a number of sectors.
The productivity mega-deduction will allow companies to expense the total cost of new investments across a number of sectors, including machinery, equipment, clean energy, zero-emission vehicles and more.
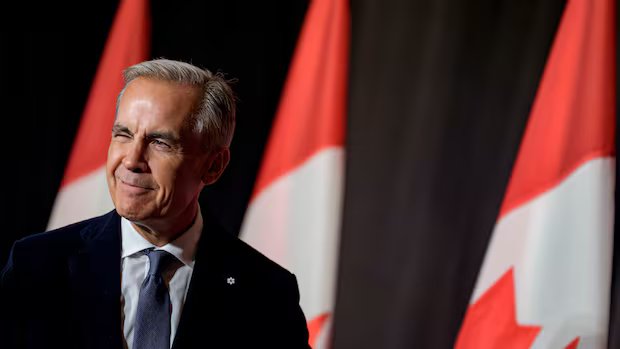
“Our goal is simple to make Canada the most attractive place in the G7 to invest,” Prime Minister Mark Carney said at the summit.
The program is an expansion of the government’s earlier productivity super-deduction outlined in last year’s budget, which initially extended to a limited selection of investments in things like equipment, machinery and technology. That meant only about 15 per cent of possible investments were covered initially, but the prime minister said the expansion means two-thirds of assets will now be eligible.
In the past, Canadian companies have been able to recoup costs over the lifetime of a project, said Randall Bartlett, deputy chief economist at Desjardins. But this program gives that money back immediately, which could free up investors to put more money into new projects.
“This is meant to provide significant incentives for companies to invest and invest very quickly,” Bartlett said.
He said that makes Canada very competitive on the tax front compared to other countries. The government says the change would slash Canada’s marginal effective tax rate — a measure of tax on businesses used to compare tax competitiveness between nations — from 13 per cent down to 6.4, making it the lowest of any country in the G7.
And that could be a big help especially amid the trade war, Bartlett said. It could give companies a reason to stay in Canada, rather than moving production south of the border, and help them make investments they’ve been holding off on due to uncertainty.
But it will also cost an estimated $36 billion over five years. Bartlett said revenue brought in from high oil prices means the extra government spending isn’t too much of an issue in the short run, but the government will have to make sure it has the coffers to sustain that kind of spending long-term.