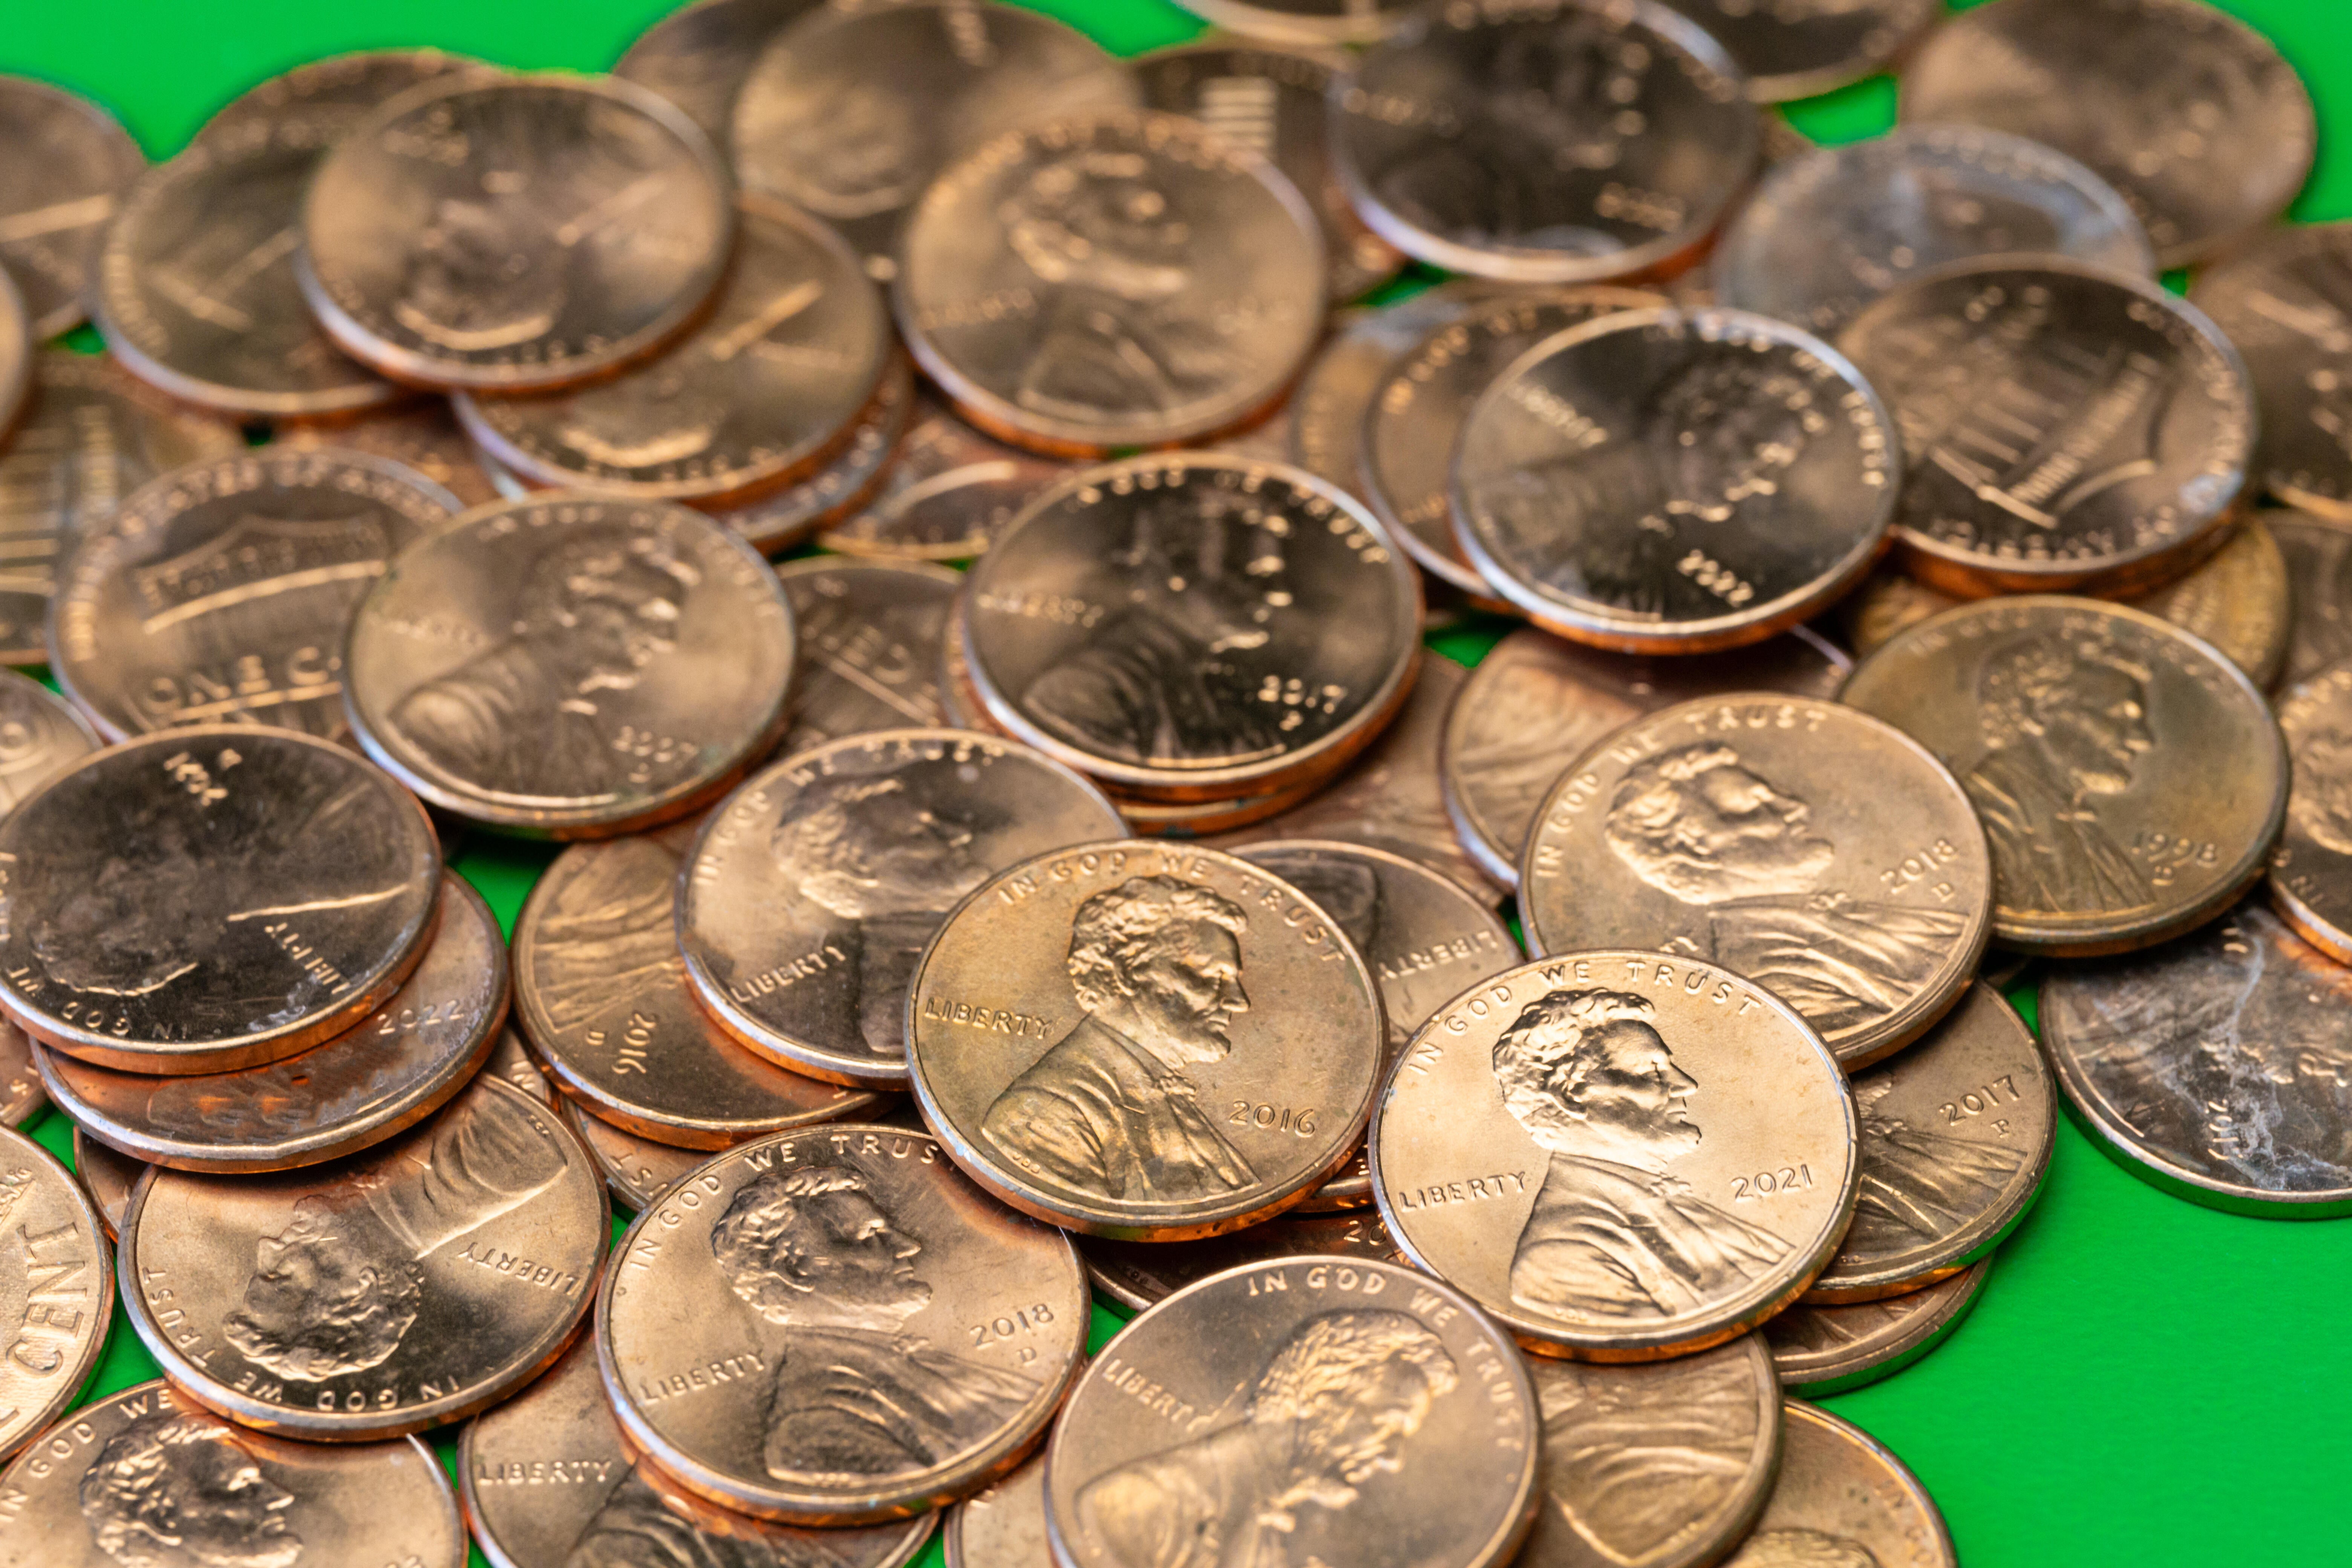
In a decisive move to reshape the landscape of American commerce, President Donald Trump signed the Common Cents Act into law, injecting federal authority into the previously fragmented domain of cash transactions. The legislation establishes comprehensive guidelines that dictate how businesses must interact with consumers when physical currency is involved, marking a significant intervention in the daily mechanics of retail and service industries. By codifying these standards at the federal level, the administration seeks to eliminate the patchwork of local regulations that have historically governed cash handling practices.
The immediate operational context of the Act spans all fifty states, imposing a uniform set of expectations on retailers, service providers, and financial institutions. This federal standardization addresses the logistical complexities that businesses face when operating across multiple jurisdictions, where cash acceptance policies and transaction limits have varied significantly. The law effectively creates a national protocol for the exchange of physical money, ensuring that consumers encounter consistent rules regardless of their geographic location.
Official remarks surrounding the signing emphasized the importance of maintaining a robust and accessible cash system in an increasingly digital economy. Stakeholders in the financial sector have begun to assess the compliance requirements, noting that the Act provides a clearer legal footing for businesses to define their cash policies while ensuring consumer protection. The initial response from industry groups suggests a cautious optimism, with many viewing the federal guidelines as a necessary stabilization measure for traditional payment methods.
In-Depth Analysis & Key Details
The historical background of the Common Cents Act reflects a growing tension between the rapid digitization of payments and the enduring reliance on physical currency. For decades, the regulation of cash transactions was largely left to state and local authorities, resulting in a complex web of differing rules that created compliance burdens for multi-state businesses. This federal intervention represents a structural shift, acknowledging that the efficiency and security of the national economy require a cohesive approach to the management of physical money, rather than leaving it to regional discretion.
Competing perspectives on the Act highlight the broader economic debate surrounding the future of money. Proponents argue that standardized cash guidelines protect consumer rights and ensure that digital payment systems do not completely marginalize cash users, preserving financial inclusion for those without access to banking or digital infrastructure. Critics, however, contend that federal mandates on transaction methods may impose unnecessary regulatory overhead on small businesses, potentially increasing operational costs. The economic consequences of this legislation will likely manifest in the form of adjusted retail policies and updated point-of-sale systems designed to meet the new federal standards.
Industry analysts observe that the technical intricacies of the Act require businesses to update their internal protocols and employee training to align with the new federal guidelines. This is not merely a legal formality but a practical operational change that affects the speed and nature of customer interactions. The regulatory debate also touches on the role of the Federal Reserve in monitoring the circulation of cash, as the Act may influence how the central bank manages the supply and distribution of physical currency to meet the demands of a standardized national system.
"The Common Cents Act marks a pivotal moment where federal policy explicitly safeguards the role of physical currency, ensuring that the transition to a digital economy does not leave behind those who rely on cash for their daily financial lives."
Why This Matters & What Lies Ahead
For everyday consumers, the Common Cents Act means greater predictability in how cash is accepted and handled across the country. This standardization can reduce confusion and friction at the point of sale, ensuring that consumers are not arbitrarily denied the use of legal tender in ways that vary by state. For financial markets, the legislation may influence investment strategies in retail technology and banking sectors, as companies adapt to the new regulatory environment. The act also has legislative implications, setting a precedent for federal involvement in other aspects of consumer financial transactions, potentially paving the way for further standardization in digital payment regulations.
Upcoming milestones to monitor include the specific implementation dates for compliance, which will determine when businesses must fully align with the new guidelines. Regulatory agencies will likely issue detailed guidance and enforcement protocols in the coming months, which will be critical for businesses to navigate the transition. Additionally, watch for potential legal challenges from state governments or industry groups that may argue the federal guidelines infringe on state sovereignty or impose undue burdens on small businesses. These developments will be crucial in understanding the long-term effectiveness and acceptance of the Common Cents Act.
Source: Reported by CBS News · Analyzed & Synthesized by DNB Newsroom