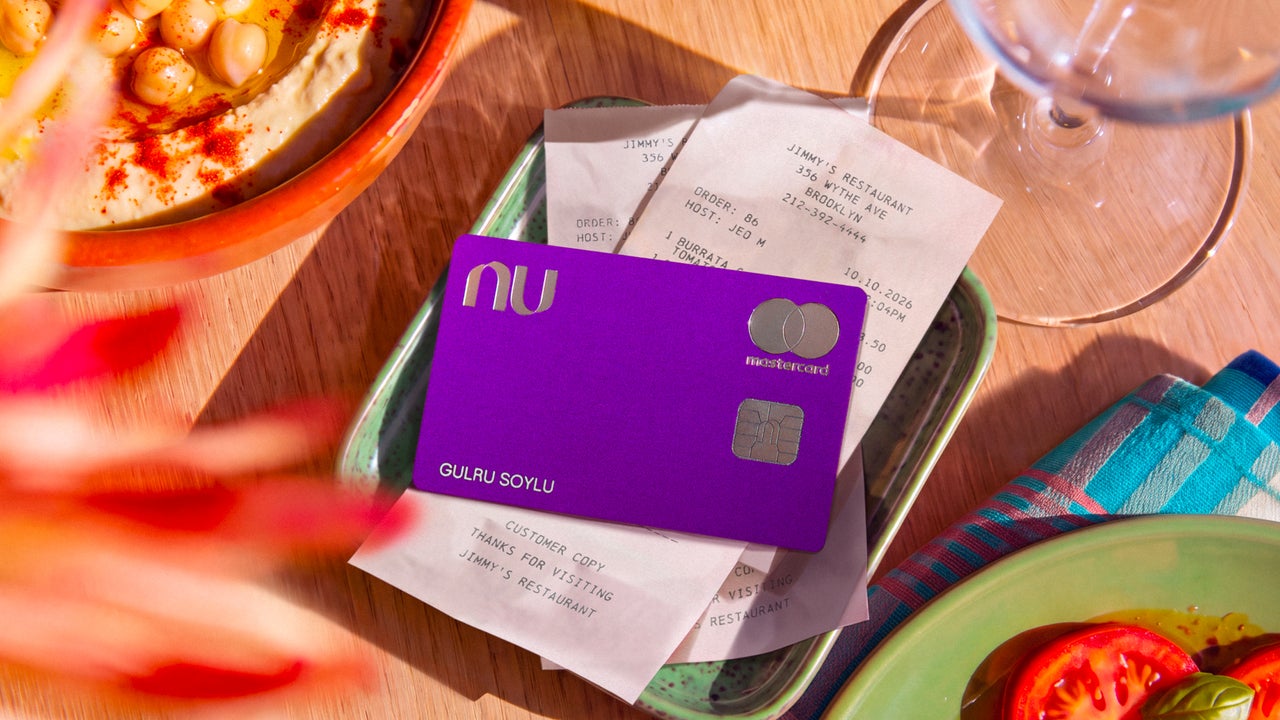
Nubank, the Brazil‑based digital bank, opened its U.S. operations on Monday as Nu after clearing a series of federal licensing, anti‑money‑laundering and consumer‑protection checks. The rollout marks the fintech’s first foray into a market dominated by legacy banks and a growing cohort of challenger institutions.
Beyond regulatory clearance, Nubank faced the practical task of building a U.S. customer‑service centre, integrating its technology stack with domestic payment networks, and training staff to meet local expectations, all while keeping the launch timeline on track.
In-Depth Analysis & Key Details
The United States imposes a layered compliance regime that forces foreign fintechs to adapt their risk‑management frameworks, capital reserves and data‑privacy policies, extending launch timelines and cost structures. Nubank’s decision to prioritize branding amid these pressures reflects a belief that visual continuity can accelerate user acquisition in a market where trust is hard won.
Industry observers note that rivals such as Revolut and Monzo have either retained their original names or adopted hybrid branding, highlighting divergent strategies. Nubank’s choice to rename but preserve the purple hue underscores a nuanced approach: a fresh legal identity to satisfy regulators, paired with a familiar visual cue to leverage existing brand equity.
"Retaining the purple hue was a strategic bet that brand familiarity outweighs the risk of a new name in a crowded market."
Why This Matters & What Lies Ahead
For American consumers, the presence of a well‑known Latin American fintech offers an alternative to traditional banks, potentially expanding access to low‑fee digital services. The launch also signals that global fintechs are willing to invest heavily in branding to win market share, which could intensify competition on price and innovation.
Regulators will monitor Nu’s compliance performance as part of its probationary period, while investors watch for user‑growth metrics and the rollout of additional products such as credit cards and small‑business loans. The next quarter’s earnings report and any amendments to U.S. fintech oversight rules will be key indicators of the venture’s long‑term viability.
Source: Reported by Fast Company · Analyzed & Synthesized by DNB Newsroom